


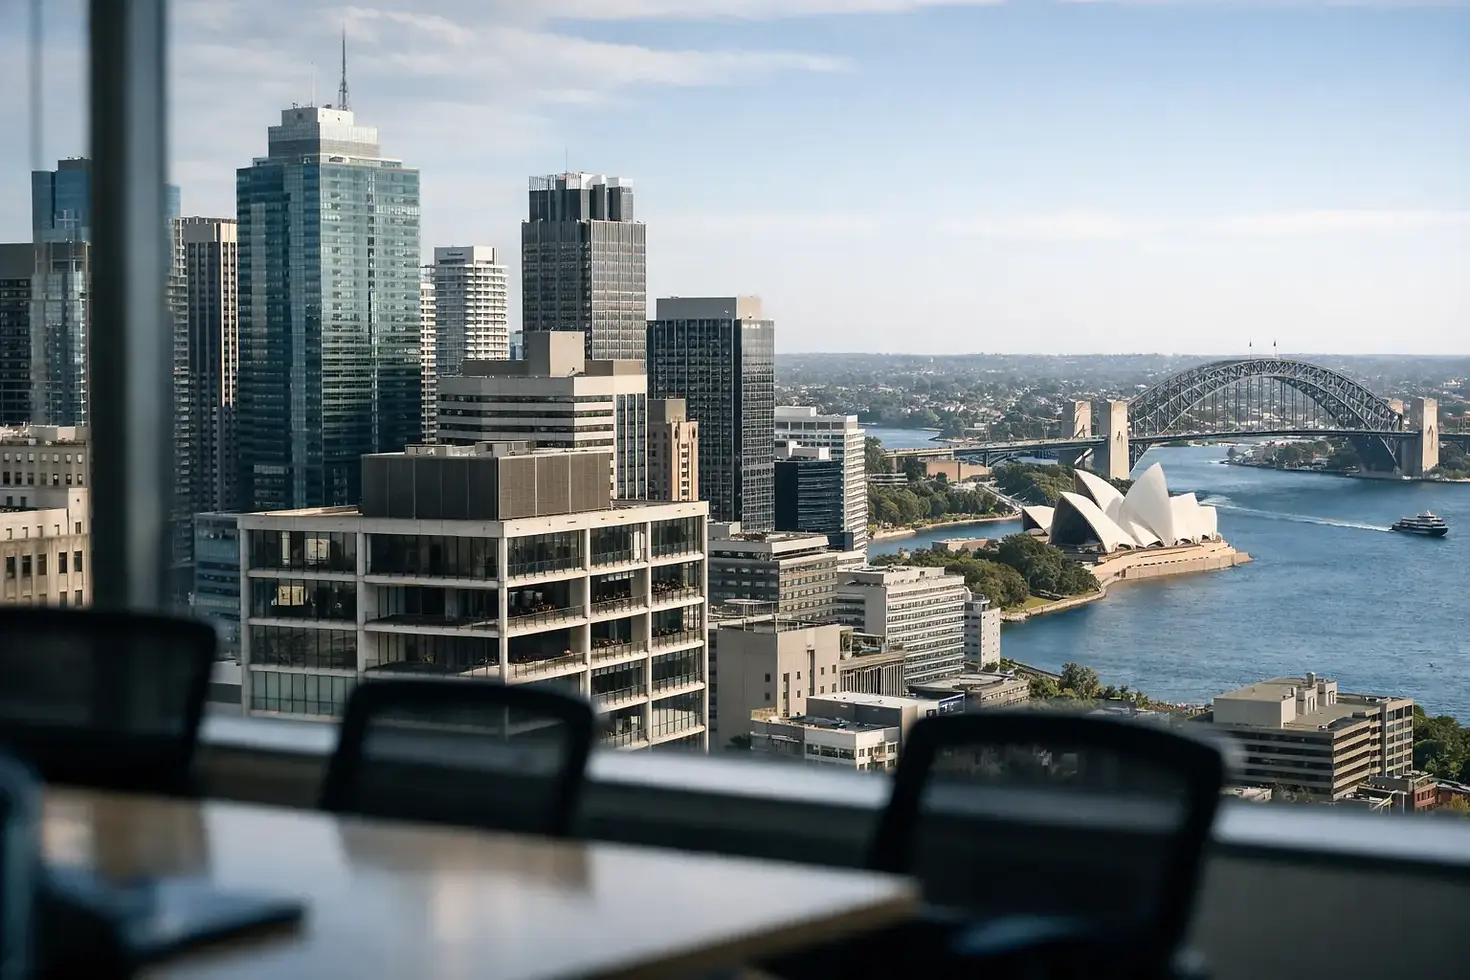
What Office Vacancy Trends Mean for Sydney
A vacant office is not simply an empty suite with a sign in the window. It is carrying costs, lost momentum and a message to the market. For tenants, it can be an opening to secure better terms. For investors, it can change the numbers behind an acquisition very quickly. That is why office vacancy trends deserve more attention than a single percentage in a market report.
In Sydney, the office market is no longer moving as one. A high-quality, well-connected workplace can compete strongly while older or poorly configured stock takes longer to lease. The practical question is not whether vacancy is rising or falling across a whole city. It is where the vacancy sits, what type of space is available and what a business will actually pay to occupy it.
Office vacancy trends are really about competing space
Headline vacancy measures are useful, but they are only a starting point. They generally show the proportion of office stock available for lease in a defined market. They do not always reveal the full competitive picture.
A landlord may have formally vacant space, while another tenant is quietly offering surplus accommodation for sublease. A building may be technically occupied but approaching a lease expiry where the occupier is actively searching for alternatives. New supply may be due to complete shortly, increasing choice before it appears in current vacancy data. These details matter because they influence the leverage each party brings to negotiation.
There is also a major difference between physical vacancy and effective availability. Effective availability includes the space a prospective tenant can realistically choose from. In a softer market, that pool can be materially larger than the published vacancy rate suggests. In a tightly held precinct or building type, the opposite can be true: plenty of space may be advertised, but little may suit the requirements of a serious occupier.
For owners, this is where a generic leasing approach can be expensive. Pricing a 500-square-metre floorplate by looking only at broad market averages ignores its presentation, floor efficiency, parking, natural light, services, building access and proximity to transport. A strong deal starts with an honest assessment of the competing options a tenant will inspect.
Sydney is a collection of office markets
Sydney CBD, North Sydney, Chatswood, Macquarie Park, Parramatta and fringe locations each respond to different demand drivers. Even within a single precinct, one side of a transport interchange can trade differently from another. Businesses do not select premises on rent alone. Staff access, customer convenience, amenity, fitout costs, branding and the ability to expand all influence the decision.
Chatswood remains particularly relevant for businesses seeking a North Shore presence with strong rail and Metro connectivity, retail amenity and access to a skilled workforce. Yet a business comparing Chatswood with the CBD or Macquarie Park may arrive with a different operational brief. One may value executive access and a professional client-facing address. Another may prioritise larger floorplates, car parking or proximity to technical teams.
This is why vacancy must be interpreted alongside enquiry quality. Ten enquiries from tenants with vague requirements are not equal to one well-capitalised business with a defined relocation timetable. Likewise, a low vacancy rate does not guarantee rental growth if local occupiers are reducing their footprint or if upcoming developments will add substantial supply.
The flight to quality has a price
Many occupiers are concentrating their expenditure on better workplaces rather than simply taking more space. They may choose a smaller, higher-quality office with collaborative areas, upgraded end-of-trip facilities, efficient air conditioning and better access to transport. This can support demand for premium and well-refurbished buildings, while creating a sharper challenge for secondary stock.
The trade-off is clear. Higher-grade space can command a stronger face rent, but it may require capital expenditure, longer incentive periods or a substantial landlord contribution to fitout. Owners should not assume that a cosmetic refresh alone will close the gap. The upgrade needs to solve a real occupier problem and be reflected in the leasing strategy.
What landlords should do when vacancy increases
When vacancy rises, the instinct is often to cut the advertised rent. That can be the right decision, but it should not be the first or only move. A poorly judged reduction can reset expectations, affect neighbouring deals and still fail to attract the right tenant.
Start by reviewing the offer as a whole: the net rent, outgoings, incentive, lease term, fitout contribution, rent-free period and make-good position. Tenants evaluate the total occupancy cost and the upfront cash required to move. A competitive package may be worth more than a lower headline rent with inflexible terms.
Presentation also matters. An empty office should make it easy for a prospect to imagine operating there. Clean finishes, clear access, accurate floor plans and an explanation of how the space can work are basic requirements. If a fitted suite can be leased as-is, quantify the saving in time and fitout expenditure. For many small and medium businesses, speed to occupation is a genuine advantage.
Landlords should also be selective about lease structure. A long lease with a weak covenant or unrealistic incentives can create more risk than a shorter arrangement with a sound tenant and clear review provisions. Legal, tax and commercial issues intersect here. Incentives, options, guarantees and make-good clauses should support the property’s long-term position, not merely fill a vacancy for the quarter.
What tenants can negotiate in a higher-vacancy market
A market with more choice gives tenants room to ask better questions. It does not automatically mean every advertised office is a bargain. A cheap premises with inadequate services, restrictive access or a costly fitout can become the most expensive option once disruption and lost productivity are considered.
Before inspecting space, a business should define its non-negotiables. How many people need to attend regularly? Is client access essential? Does the operation need meeting rooms, secure storage, loading access or parking? Will hybrid work change the required area over the next three years? A clear brief prevents a tenant from being distracted by a headline incentive attached to unsuitable premises.
The strongest tenant negotiations compare genuine alternatives and keep timing under control. If a lease expiry is only weeks away, the landlord knows it. Beginning early allows the tenant to assess renewal, relocation and sublease options with real leverage. It also creates time to negotiate practical items often overlooked in the initial rent discussion, including after-hours air conditioning, signage, fitout approvals, reinstatement obligations and rights to assign or sublet.
For tenants considering a move, the existing lease deserves as much attention as the new one. Make-good exposure, notice dates and holding-over provisions can materially alter the economics of relocation. A good deal is not simply the office with the largest rent-free period. It is the arrangement that supports the business without leaving an avoidable liability behind.
Investors need to separate vacancy from risk
Office vacancy can create opportunity for investors, particularly where a building is well located but under-managed, poorly marketed or carrying short-term vacancy that can be addressed. However, vacant space is not automatically value-add. It may indicate an obsolete layout, major capital works ahead, weak building services or a precinct facing structural demand changes.
Due diligence should test the rent roll against upcoming expiries, current incentives, tenant covenants and the cost of returning space to market. It should also examine comparable deals, not just advertised asking rents. A building may appear to have secure income, yet contain tenants paying above market rents who are unlikely to renew without a concession.
The right acquisition strategy depends on whether the vacancy is cyclical, asset-specific or structural. Cyclical vacancy may respond to patient leasing and sensible incentives. Asset-specific vacancy may be fixed through refurbishment, repositioning or better management. Structural vacancy requires greater caution because no amount of marketing will overcome a location or building that no longer meets occupier needs.
Read the data, then inspect the reality
Market reports provide useful direction, but property decisions should be made at street level and building level. Ask how much available space is fitted, what tenants are actually transacting, which leases expire soon and whether incentives are rising or falling. Inspect the competing premises. Speak with operators who understand the local enquiry pool rather than relying on a citywide number.
At William Properties, that practical assessment is central to how we advise owners, tenants and investors. The right strategy comes from understanding the property, the deal and the people who need to make it work.
The next move should be deliberate: assess the alternatives, know your costs and negotiate from evidence rather than noise.


Comments